
Lamb Weston’s Turnaround Is Starting to Look Real
Lamb Weston (NYSE: LW) has its share of issues, not least of all the lingering impact of the botched rollout of its enterprise resource planning (ERP) platform, which is now more of a mental hang-up than anything else. It also has an active turnaround strategy, supported by activist investors, that is starting to show results.
While sales remain sluggish, margins are improving, setting the stage for accelerated earnings growth in upcoming quarters. The capital return capacity is healthy and improving quarterly, enabling dividends and share buybacks, the primary reason for owning consumer staples stocks.
Trading at about 15x current-year earnings guidance, LW stock is a deep-value opportunity, with the market pricing in failure rather than recovery. What the market is missing is that this company isn't broken, but rather suffering from self-inflicted wounds that it can and will recover from.
Looking forward, investors can expect steady revenue growth, margin recovery, and accelerated earnings growth over time—and the capital returns that come with it.
Lamb Weston: An Early-Stage Dividend Growth Machine
Lamb Weston is a committed dividend payer and dividend growth machine, with eight consecutive annual increases since its spin-off and the ninth coming down the pipe. The opportunity for investors is to get on board now, while it's still early in the game, as history suggests the stock price will rise given the company's capital-return growth trajectory.
In this scenario, consistency, annual increases, and yield drive rising ownership, with ownership accelerating as periodic milestones are reached. These include the 10th, 15th, and 25th consecutive years of distribution increases; thresholds for inclusion in key indices like the Dividend Achievers, Dividend Aristocrats, and Dividend Kings; and triggers for index-related and buy-and-hold investing.
Lamb Weston did not buy back significant shares in Q1 of its fiscal 2027 (FY2027) but is on track to reduce the count this year. Trailing 12-month activity reduced the count by 1.2%, and $245 million remains under the remaining authorization, worth about 4% of the early October market cap. Balance sheet highlights reflect capacity for buybacks to continue, with cash and assets increasing, and liabilities and equity steady.
Among Lamb Weston’s risks is its debt. While not excessively high, it is a headwind that could quickly become a problem if the company makes further missteps. The offset is that strategy execution is driving results, providing better clarity into future profitability and debt coverage. As it is, the company’s cash flow is sufficient; the debt is merely a concern dragging on sentiment.
Lamb Weston Outperforms, Raises Guidance in Fiscal Q1
Lamb Weston didn’t have a robust quarter but posted nearly 1% growth and outperformed estimates while improving operations. Growth was centered in North America, which grew by 5% and accounts for about 65% of the total business. Volume also rose 2%, offset by price/mix and weakness in the International segment. International business contracted by 8%, hurt by regional demand, high crop yields, and carrying costs linked to capacity utilization.
Margin was a bright spot, down year over year (YOY) due to rising cost pressures, but less than expected. Key takeaways include $280 million in adjusted EBITDA, $103 million in adjusted net income, flat YOY and sufficient for an approximate 50% dividend payout ratio. Other bullish factors include 75 cents in adjusted earnings per share, up 2 cents YOY (about 1%) and more than 15 cents above MarketBeat’s consensus forecast.
Looking ahead, the company expects the strengths to continue and has lifted its full-year guidance. Execs now expect low single-digit growth versus the prior outlook of flat to 1% growth, with adjusted earnings of $3.05 at the low end, nearly a nickel above forecasts and potentially cautious.
Lamb Weston Stock Sends Signal After Earnings Results
The market response following the earnings release highlights the strength of Lamb Weston's Q1 FY2027 results. The stock gained more than 10%, confirming support in the low-$40s and the potential for a complete reversal. The next hurdle is existing highs in the mid-$50s, likely reached before the year's end. A move above $50 would signal a shift in market dynamics and likely lead to a sustainable rally.
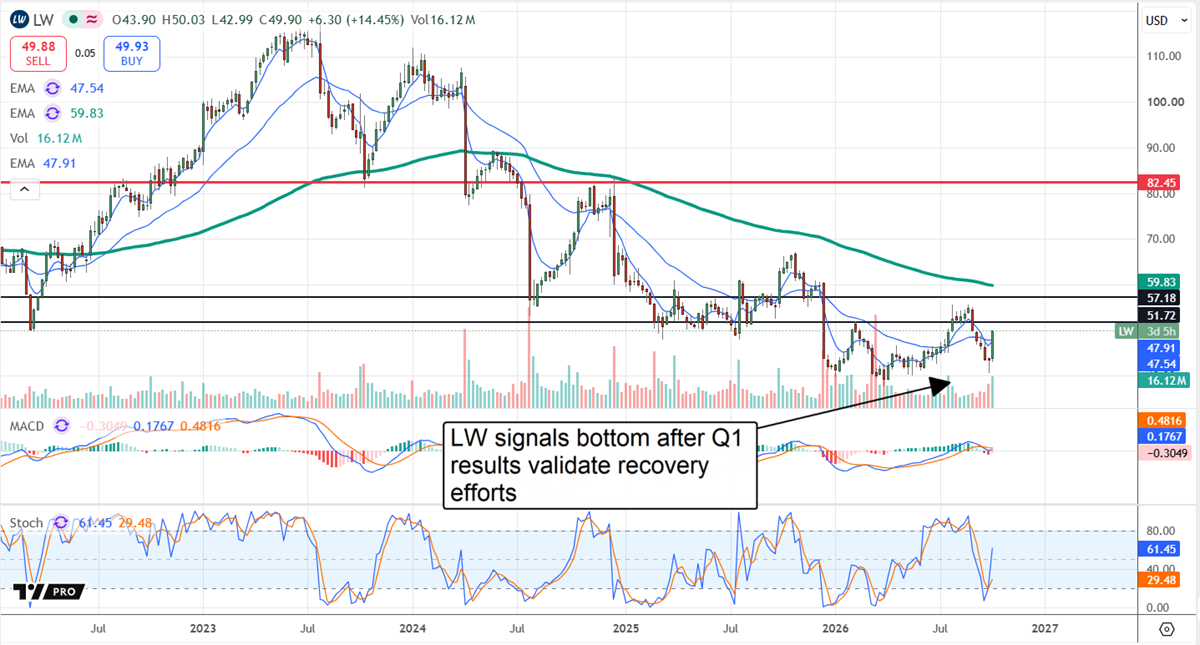
Risks for investors to be aware of include the status of the ERP rollout, which has been paused, and its long-term ramifications. Not only were client relationships damaged, but class-action lawsuits against the company and its executives can proceed. Investors allege the company misled the market about the inherent risks, including system failures. The next visible catalyst is the upcoming investor day scheduled for early in 2027. Execs are expected to give updates on Europe, ERP initiatives, and strategic progress.
Where Should You Invest $1,000 Right Now?
Before you make your next trade, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis.
Our team has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and none of the big name stocks were on the list.
They believe these five stocks are the five best companies for investors to buy now...
