
Bull of the Day: BP plc (BP)
BP p.l.c. BP has a new CEO and a strategy to reduce debt as oil prices remain high. Analysts are raising 2026 earnings estimates again on this Zacks Rank #1 (Strong Buy).
BP is a global energy company with oil and natural gas exploration and production, refining, service stations, EV charging, and convenience stores, as well as supply, trading, and shipping.
It’s global brands include bp, bp connect, bp pulse, Castrol, Aral, Amoco, AMPM convenience stores, Thorntons, wildbean café, Air bp, and TravelCenters of America.
BP Beat Again in the Second Quarter of 2026
On Aug 4, 2026, BP reported its second quarter 2026 results and beat on the Zacks Consensus Estimate by $0.24. Earnings were $2.22 versus the consensus of $1.98.
It was the company’s fifth consecutive earnings beat.
This was also the first full quarter for the new CEO Meg O’Neill, who took the helm in April of 2026.
There’s a new strategy to pay down the debt and achieve a more attractive balance sheet.
In the second quarter, net debt fell to $22.25 billion from $25.3 billion at the end of the first quarter.
BP is also divesting some business segments. It reached an agreement to sell the Austrian retail business, completed the sale of the Gelsenkirchen refinery in German, is actively looking to off load the North Sea business and Archaea Energy, the biogas business it acquired in 2022 for $4.1 billion.
Analysts Raise 2026 Earnings Estimates This Week
With WTI crude remaining around $90 and Brent around $100, it appears that oil will remain higher for longer. That means higher earnings for BP.
The analysts are bullish.
Three earnings estimates were raised for 2026 in the last week. That pushed the Zacks Consensus up to $7.28 from $6.74 in the last seven days.
But the most accurate estimate is calling for $7.37, which is higher than the Zacks Consensus.
This is earnings growth of 152.8% as BP made just $2.88 last year.
Here’s what it looks like on the 5-year price and consensus chart.
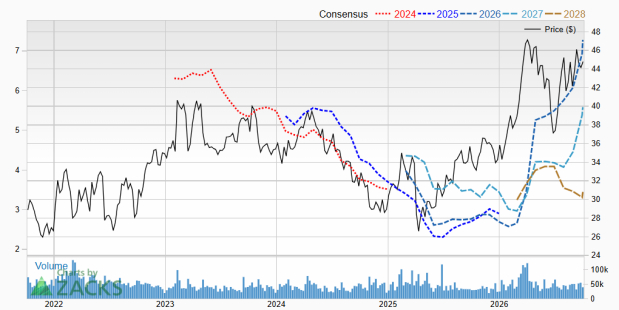
Image Source: Zacks Investment Research
BP Remains a Value Stock
Shares of BP have rallied this year, gaining 24.5% but it’s been a volatile ride as you can see from the chart.
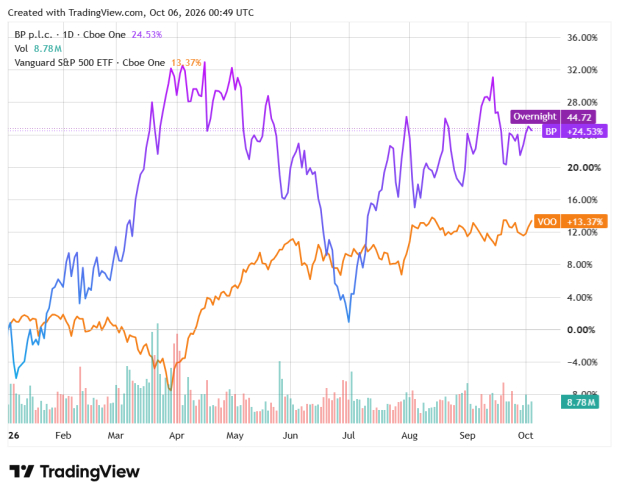
Image Source: Zacks Investment Research
It’s a cheap stock. BP has a forward price-to-earnings (P/E) of 6.2. A P/E under 10 means a company is dirt cheap.
The company also has other value fundamentals such as a price-to-sales (P/S) ratio of 0.5. A P/S ratio under 1.0 means you are getting $1.00 worth of sales for just $0.50.
BP is also shareholder friendly. It suspended its share repurchases earlier this year in order to pay down debt.
But it’s still paying a dividend of $2.06 a year, which is yielding 4.6%.
For investors looking for a way to play higher oil and refined products prices, BP should be on your short list.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>BP p.l.c. (BP) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
